
TABLE OF CONTENTS
Introduction
The global bond market has moved to the center of financial attention as long-term government borrowing costs climb toward levels not seen for many years. The immediate pressure is most visible in the United States, Europe and Japan, but the implications extend far beyond government debt markets.
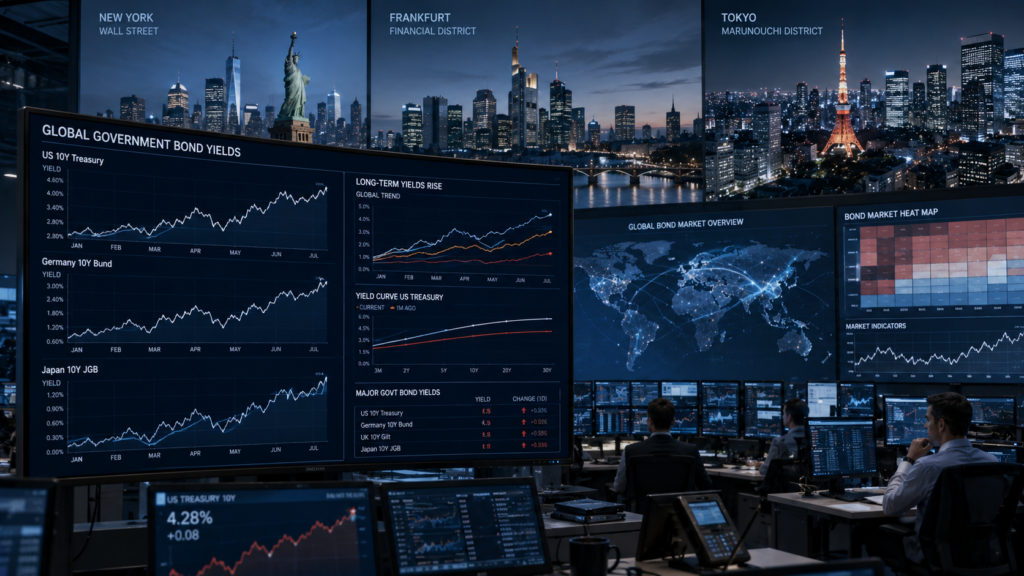
On August 19, the U.S. 30-year Treasury yield was around 5.27%, after reaching 5.3371% the previous day, its highest level in nearly two decades. German and French long-term yields have also been elevated, while Japan’s 10-year government bond yield has moved toward the 3% level.
The key question is no longer simply whether bond prices are falling.
The Global Bond Market Selloff is therefore becoming a broader test of how investors price government debt, inflation and long-term economic risk.
The larger question is what happens when the world’s biggest economies must pay substantially more to borrow money at the same time that governments, corporations and technology companies are demanding enormous amounts of capital. The Global Bond Market Selloff
Why the Global Bond Market Selloff Matters
A bond selloff means bond prices fall and yields rise.
That relationship is important because long-term government bond yields influence the cost of money throughout the economy. Mortgage rates, corporate borrowing, infrastructure financing and valuations of long-duration assets can all be affected when benchmark yields move higher.
Reuters notes that long-end sovereign yields serve as an important anchor for many other financial assets and are closely connected with mortgage rates and broader financing conditions.
This makes the current market move much bigger than a technical bond-market event.
If governments have to offer investors higher returns, companies may also need to pay more to raise capital. Consumers can eventually face higher borrowing costs as well. The current Global Bond Market Selloff
The result can be tighter financial conditions even without an immediate increase in short-term policy rates.
1. Government Debt Is Becoming More Expensive
One of the strongest forces behind the current bond-market pressure is concern about government debt.
Large economies are issuing substantial quantities of debt to finance budget requirements, while investors are becoming increasingly sensitive to the long-term fiscal outlook.
The Wall Street Journal reported that U.S. long-term yields have reached levels not seen in many years amid concerns about inflation, government deficits and increased corporate debt issuance.
The problem is particularly important for countries that already carry enormous debt loads.
When interest rates remain high, governments must refinance existing debt at higher costs while also paying more on newly issued debt.
That can create a feedback loop:
Higher yields → higher interest costs → greater fiscal pressure → more investor concern → potentially higher yields.
The process does not automatically become a crisis, but it can make fiscal management substantially more difficult.
The Global Bond Market Selloff adds to that pressure by making new government borrowing and debt refinancing more expensive.
The Global Bond Market Selloff is affecting…
2. Inflation Is Still a Major Bond-Market Risk
Inflation remains another major reason investors are demanding higher yields.
Higher inflation reduces the real value of future fixed payments from bonds. Investors therefore generally demand greater compensation when they believe inflation may remain elevated.
Current oil-market conditions are adding to those concerns.
Brent crude has remained above $90 per barrel amid tensions surrounding the Strait of Hormuz, increasing fears that energy costs could continue feeding inflationary pressure.
That creates a difficult environment for central banks. Another consequence of the Global Bond Market Selloff…
If inflation remains stubborn, monetary authorities may have less freedom to cut rates aggressively.
At the same time, keeping monetary policy restrictive for longer can increase pressure on interest-sensitive parts of the economy.
3. The AI Boom Is Also Changing the Bond Market
One of the most interesting elements of the current story is the relationship between artificial intelligence investment and the bond market.
The AI infrastructure buildout requires enormous amounts of capital.
Data centers, computing infrastructure, electricity systems and advanced semiconductor capacity all require long-term investment.
Technology companies and AI hyperscalers have increasingly turned to debt markets to finance part of that expansion.
MarketWatch reported that major hyperscalers could issue hundreds of billions of dollars in bonds over the coming years, creating additional competition for investors’ capital.
The Financial Times similarly highlighted the growing supply of long-dated corporate bonds from technology companies financing AI investment.
This creates an unusual situation.
The world’s governments need to sell bonds.
For investors, the Global Bond Market Selloff…
At the same time, some of the world’s largest technology companies also need to sell bonds.
Investors therefore have more long-term debt securities competing for capital.
If supply increases faster than demand, issuers may have to offer higher yields to attract buyers.
4. Japan Has Become an Important Warning Signal
Japan is particularly important because its bond market has historically been associated with exceptionally low interest rates.
That environment encouraged Japanese investors to invest internationally.
But Japan’s long-term yields have now moved sharply higher.
The 10-year Japanese government bond yield has approached 3%, a level that would have seemed extraordinary compared with the country’s long period of ultra-low rates.
This matters globally because Japanese investors have historically been important participants in overseas debt markets.
If domestic Japanese yields become more attractive, some capital may remain at home rather than flowing into foreign bonds.
That could contribute to higher borrowing costs elsewhere.
5. Europe Is Facing the Same Structural Pressure
The bond-market pressure is not an American story.
Germany’s 10-year Bund yield recently reached levels not seen since 2011, while France has also experienced significant increases in long-term yields.
European governments are simultaneously dealing with fiscal demands, energy uncertainty and geopolitical risks.
The result is a difficult balancing act. The longer the Global Bond Market Selloff continues…
Governments need investment and public spending to support economic activity, but investors increasingly want compensation for the risks associated with higher debt and uncertain inflation.
That tension can push borrowing costs higher.
6. Rising Yields Are Starting to Pressure Stocks
The bond market does not operate in isolation.
When safe government bonds offer higher yields, investors can reassess the attractiveness of equities.
This is particularly important for technology companies whose valuations depend heavily on expectations of future earnings.
Higher discount rates reduce the present value investors assign to future cash flows.
That helps explain why technology and semiconductor shares have recently come under pressure alongside rising bond yields.
Reuters reported that Japan’s Nikkei fell 3.3% and South Korea’s KOSPI dropped nearly 6% on August 19, with semiconductor weakness contributing to the decline.
The Financial Times also reported significant declines in U.S. semiconductor shares as long-term government yields climbed.
The connection is therefore straightforward:
Higher yields can increase financing costs while simultaneously reducing the valuation premium investors are willing to pay for high-growth assets.
The Global Bond Market Selloff matters for equities because higher long-term yields can change the relative attractiveness of stocks, especially in high-growth sectors.
7. What Happens to Businesses?
Companies with large financing requirements could face a more difficult environment.
Businesses that need to refinance debt may discover that their interest costs are higher.
Companies planning major infrastructure projects may need to reconsider the timing or financing structure of those investments.
Smaller companies can be particularly vulnerable because they often borrow at higher spreads than governments and large corporations.
However, higher yields are not negative for everyone.
Banks, insurers and savers can potentially benefit from higher returns on certain fixed-income assets.
The economic impact therefore depends on whether an individual, company or institution is a borrower or a lender.
8. What Does It Mean for Consumers?
The bond market can eventually reach households through borrowing costs.
Mortgage rates can rise when long-term government yields increase.
Business loans can become more expensive.
Consumer credit conditions can tighten.
Housing markets can become more sensitive because higher mortgage payments reduce the amount buyers can afford.
This is why the bond-market selloff deserves attention even from people who do not own government bonds.
The price of long-term money affects the entire economy.
The Bigger Economic Question
The most important issue is whether the current bond-market pressure represents a temporary repricing or the beginning of a longer global rate reset.
There are arguments for both possibilities.
The immediate pressure comes from inflation concerns, higher oil prices, fiscal deficits, increased debt issuance and uncertainty about monetary policy.
But some analysts argue that the rise in long-term yields is part of a longer structural trend rather than a single sudden shock.
Axios described the development as a broader global rate reset in which the cost of borrowing over long periods has been rising across major economies.
That distinction matters.
If the move is temporary, markets could stabilize once inflation expectations moderate and investors become more comfortable with government debt.
If it is structural, governments and companies may have to operate in a world where cheap long-term money is no longer the default assumption.
A prolonged Global Bond Market Selloff would reinforce that shift by keeping long-term financing costs elevated across major economies.
What Markets Are Watching Next
Several developments will determine the next stage.
First, investors will watch inflation data closely.
Second, oil prices remain critical because sustained energy inflation could complicate monetary policy.
Third, markets will watch central-bank communication and the Federal Reserve’s policy direction.
Fourth, government bond auctions will provide direct evidence of investor demand.
Reuters reported that the U.S. Treasury was scheduled to auction $16 billion of 20-year debt on August 19, making demand at the auction an important market signal.
Finally, investors will continue watching corporate debt issuance from major technology companies.
The combination of government borrowing and AI-related corporate borrowing could remain one of the defining features of the global capital market in 2026.
The Bigger Picture
The global bond market selloff is more than a story about rising yields.
It represents a confrontation between government debt, inflation, energy costs, AI investment, corporate borrowing and investor demand for long-term capital.
The world is entering an era in which enormous investments are required for energy, technology, defense, infrastructure and digital transformation.
But those investments are arriving at the same time that the cost of long-term financing is increasing.
That creates a major economic challenge.
For governments, the question is how to control debt while continuing to invest.
For corporations, the question is how to finance growth without becoming overly dependent on expensive debt.
For investors, the question is how to balance risk and return in a world where government bonds once again offer increasingly competitive yields.
And for consumers, the issue may eventually appear in the form of mortgages, loans, housing prices and business costs.
The immediate bond-market selloff may stabilize.
But the deeper transformation could be more lasting: the global economy may be moving from an era of exceptionally cheap money toward an era in which capital has a much higher price.
That could become one of the defining economic stories of 2026.
INTERNAL READING
For more analysis from FACELESS MATTERS, explore our related coverage on Pakistan’s digital economy, economic developments and major institutional changes. These stories provide additional context for readers following the wider economic and strategic environment.
1 — Pakistan Digital Economy Initiative 2026: Powerful Digital Growth
2 — Pakistan Independence Day 2026: Courage, Sacrifice & Unity
3 — The Role of Institutions and Citizens in Ending Pakistan Terrorism
4 — The AI Infrastructure Boom: Nvidia, OpenAI and the Global Race for Data Centers, Chips and Power
SOURCE VERIFICATION & ANALYSIS
Reuters — Global bond markets and rising sovereign yields, August 19, 2026.
Financial Times — Global borrowing costs and bond-market selloff, August 19, 2026.
Wall Street Journal — Global bond-market pressure and long-term yields, August 19, 2026.
MarketWatch — U.S. Treasury yields and global bond selloff, August 18–19, 2026.
Investopedia — Treasury yields and implications for borrowers and investors, August 19, 2026.
Associated Press — Asian markets, bond yields and oil prices, August 19, 2026.
Axios — Global long-term borrowing-cost reset, August 18, 2026.
Reuters — European equities, bond yields and fiscal concerns, August 18, 2026.
Economic Times — U.S. fiscal outlook and Treasury borrowing costs, August 19, 2026.
FACELESS MATTERS — Existing economic and strategic coverage used for internal contextual linking.
EDUCATIONAL NOTE
This article is for educational, informational and economic-awareness purposes only. It does not constitute financial, investment, legal or tax advice. Market conditions can change rapidly, and readers should independently verify financial information before making decisions.
[…] Global Bond Market Selloff: Why Borrowing Costs Are Rising in 2026Use this as a macroeconomic connection because Treasury yields and liquidity directly affect crypto […]
[…] Global Bond Market Selloff: Why Borrowing Costs Are Rising in 2026Use this as a macroeconomic connection because Treasury yields and liquidity directly affect crypto […]
[…] Global Bond Market Selloff: Why Borrowing Costs Are Rising in 2026یہ مضمون جغرافیائی کشیدگی، مہنگائی، شرح سود، بانڈ […]
[…] Global Bond Market Selloff: Why Borrowing Costs Are Rising in 2026 […]
[…] Global Bond Market Selloff: Why Borrowing Costs Are Rising in 2026 […]
[…] 2. Global Bond Market Selloff: Why Borrowing Costs Are Rising in 2026یہ مضمون جغرافیائی کشیدگی، مہنگائی، شرح سود، بانڈ مارکیٹ اور عالمی مالیاتی حالات کے تعلق کو واضح کرے گا۔ […]
[…] 3. Global Bond Market Selloff: Why Borrowing Costs Are Rising in 2026Geopolitical tensions، inflation، borrowing costs اور عالمی financial markets کے تعلق کو مزید سمجھنے کے لیے متعلقہ مضمون ہے۔ Global Bond Market Selloff: Why Borrowing Costs Are Rising in 2026 […]
[…] Pakistan Digital Economy Initiative 2026: Powerful Digital Growth […]
[…] Global Bond Market Selloff: Why Borrowing Costs Are Rising in 2026Use this as a macroeconomic connection because Treasury yields and liquidity directly affect crypto […]